Business
A central bank digital euro could save the eurozone – here’s how
Published
4 years agoon
The European Central Bank and its counterparts in the UK, US, China and India are exploring a new form of state-backed money built on similar online ledger technology to cryptocurrencies such as bitcoin and ethereum.
So-called central bank digital currencies (CBDCs) envision a future where we’ll all have our own digital wallets and transfer money between them at the touch of a button, with no need for high-street banks to be involved because it all happens on a blockchain.
But CBDCs also present an opportunity that has gone unnoticed – to vastly reduce the exorbitant levels of public debt weighing down many countries. Let us explain.
The idea behind CBDCs is that individuals and firms would be issued with digital wallets by their central bank with which to make payments, pay taxes and buy shares or other securities. Whereas with today’s bank accounts, there is always the outside possibility that customers are unable to withdraw money because of a bank run, that can’t happen with CBDCs because all deposits would be 100% backed by reserves.
Today’s retail banks are required to keep little or no deposits in reserve, though they do have to hold a proportion of their capital (meaning easily sold assets) as protection in case their lending books run into trouble. For example, eurozone banks’ minimum requirement is 15.1%, meaning if they have capital of €1 billion (£852 million), their lending book cannot exceed €6.6 billion (that’s 6.6 times deposits).
In an era of CBDCs, we assume that people will still have bank accounts – to have their money invested by a fund manager, for instance, or to make a return by having it loaned out to someone else on the first person’s behalf. Our idea is that the 100% reserve protection in central bank wallets should extend to these retail bank accounts.
That would mean that if a person put 1,000 digital euros into a retail bank account, the bank could not multiply that deposit by opening more accounts than they could pay upon request. The bank would have to make money from its other services instead.
At present, the ECB holds about 25% of EU members’ government debt. Imagine that after transitioning to a digital euro, it decided to increase this holding to 30% by buying new sovereign bonds issued by member states.
To pay for this, it would create new digital euros – just like what happens today when quantitative easing (QE) is used to prop up the economy. Crucially, for each unit of central bank money created in this way, the money circulating in the wider economy increases by a lot more: in the eurozone, it roughly triples.
This is essentially because QE drives up the value of bonds and other assets, and as a result, retail banks are more willing to lend to people and firms. This increase in the money supply is why QE can cause inflation.
If there was a 100% reserve requirement on retail banks, however, you wouldn’t get this multiplication effect. The money created by the ECB would be that amount and nothing more. Consequently, QE would be much less inflationary than today.
The debt benefit
So where does national debt fit in? The high national debt levels in many countries are predominantly the result of the global financial crisis of 2007-09, the eurozone crisis of the 2010s and the COVID pandemic. In the eurozone, countries with very high debt as a proportion of GDP include Belgium (100%), France (99%), Spain (96%), Portugal (119%), Italy (133%) and Greece (174%).
One way to deal with high debt is to create a lot of inflation to make the value of the debt smaller, but that also makes citizens poorer and is liable to eventually cause unrest. But by taking advantage of the shift to CBDCs to change the rules around retail bank reserves, governments can go a different route.
The opportunity is during the transition phase, by reversing the process in which creating money to buy bonds adds three times as much money to the real economy. By selling bonds in exchange for today’s euros, every one euro removed by the central bank leads to three disappearing from the economy.
Indeed, this is how digital euros would be introduced into the economy. The ECB would gradually sell sovereign bonds to take the old euros out of circulation, while creating new digital euros to buy bonds back again. Because the 100% reserve requirement only applies to the new euros, selling bonds worth €5 million euros takes €15 million out of the economy but buying bonds for the same amount only adds €5 million to the economy.
However, you wouldn’t just buy the same amount of bonds as you sold. Because the multiplier doesn’t apply to the bonds being bought, you can triple the amount of purchases and the total amount of money in the economy stays the same – in other words, there’s no extra inflation.
For example, the ECB could increase its holdings of sovereign debt of EU member states from 25% to 75%. Unlike the sovereign bonds in private hands, member states don’t have to pay interest to the ECB on such bonds. So EU taxpayers would now only need to pay interest on 25% of their bonds rather than the 75% on which they are paying interest now.
Interest rates and other questions
An added reason for doing this is interest rates. While interest rates payable on bonds have been meagre for years, they could hugely increase on future issuances due to inflationary pressures and central banks beginning to raise short-term interest rates in response. The chart below shows how the yields (meaning rates of interest) on the closely watched 10-year sovereign bonds for Spain, Greece, Italy and Portugal have already increased between three and fivefold in the past few months.
Following several years of immense shocks from the pandemic, the energy crisis and war emergency, there’s a risk that the markets start to think that Europe’s most indebted countries can’t cover their debts. This could lead to widespread bond selling and push interest rates up to unmanageable levels. In other words, our approach might even save the eurozone.
The ECB could indeed achieve all this without introducing a digital euro, simply by imposing a tougher reserve requirement within the current system. But by moving to a CBDC, there is a strong argument that because it’s safer than bank deposits, retail banks should have to guarantee that safety by following a 100% reserve rule.
Note that we can only take this medicine once, however. As a result, EU states will still have to be disciplined about their budgets.
Instead of completely ending fractional reserve banking in this way, there’s also a halfway house where you make reserve requirements more stringent (say a 50% rule) and enjoy a reduced version of the benefits from our proposed system. Alternatively, after the CBDC transition ends, the reserve requirement could be progressively relaxed to stimulate the economy, subject to GDP growth, inflation and so on.
What if other central banks do not take the same approach? Certainly, some coordination would help to minimise disruption, but reserve requirements do differ between countries today without significant problems. Also, many countries would probably be tempted to take the same approach. For example, the Bank of England holds over one-third of British government debt, and UK public debt as a proportion of GDP currently stands at 95%.
The authors do not work for, consult, own shares in or receive funding from any company or organization that would benefit from this article, and have disclosed no relevant affiliations beyond their academic appointment.
Copyright © 2010–2022, The Conversation Trust (UK) Limited
Announcements
Dubai-born HOP Events targets 25 cities in global expansion
Published
1 day agoon
October 2, 2026
A Dubai-founded events company is planning to expand into 25 cities worldwide over the next two years, as it looks to build an international business around music and culture.
HOP Events, founded by Dubai-based entrepreneur Kalpesh Kinariwala, said it aims to stage more than 250 events a year across 75 venues and arenas, reaching more than one million people annually.
Its planned expansion includes London, New York, Doha and Singapore, alongside its existing base in Dubai.
The company has organised concerts featuring artists including A.R. Rahman, Arijit Singh, Lucky Ali, Nancy Ajram, Rahat Fateh Ali Khan and sitarist Rishab Sharma.
HOP now plans to broaden its programme beyond large-scale concerts, with storytelling, art and other cultural events forming part of its international expansion.
“Our goal has never been to build an events company,” Kinariwala said. “We’re building a platform where culture becomes a catalyst for connection.”
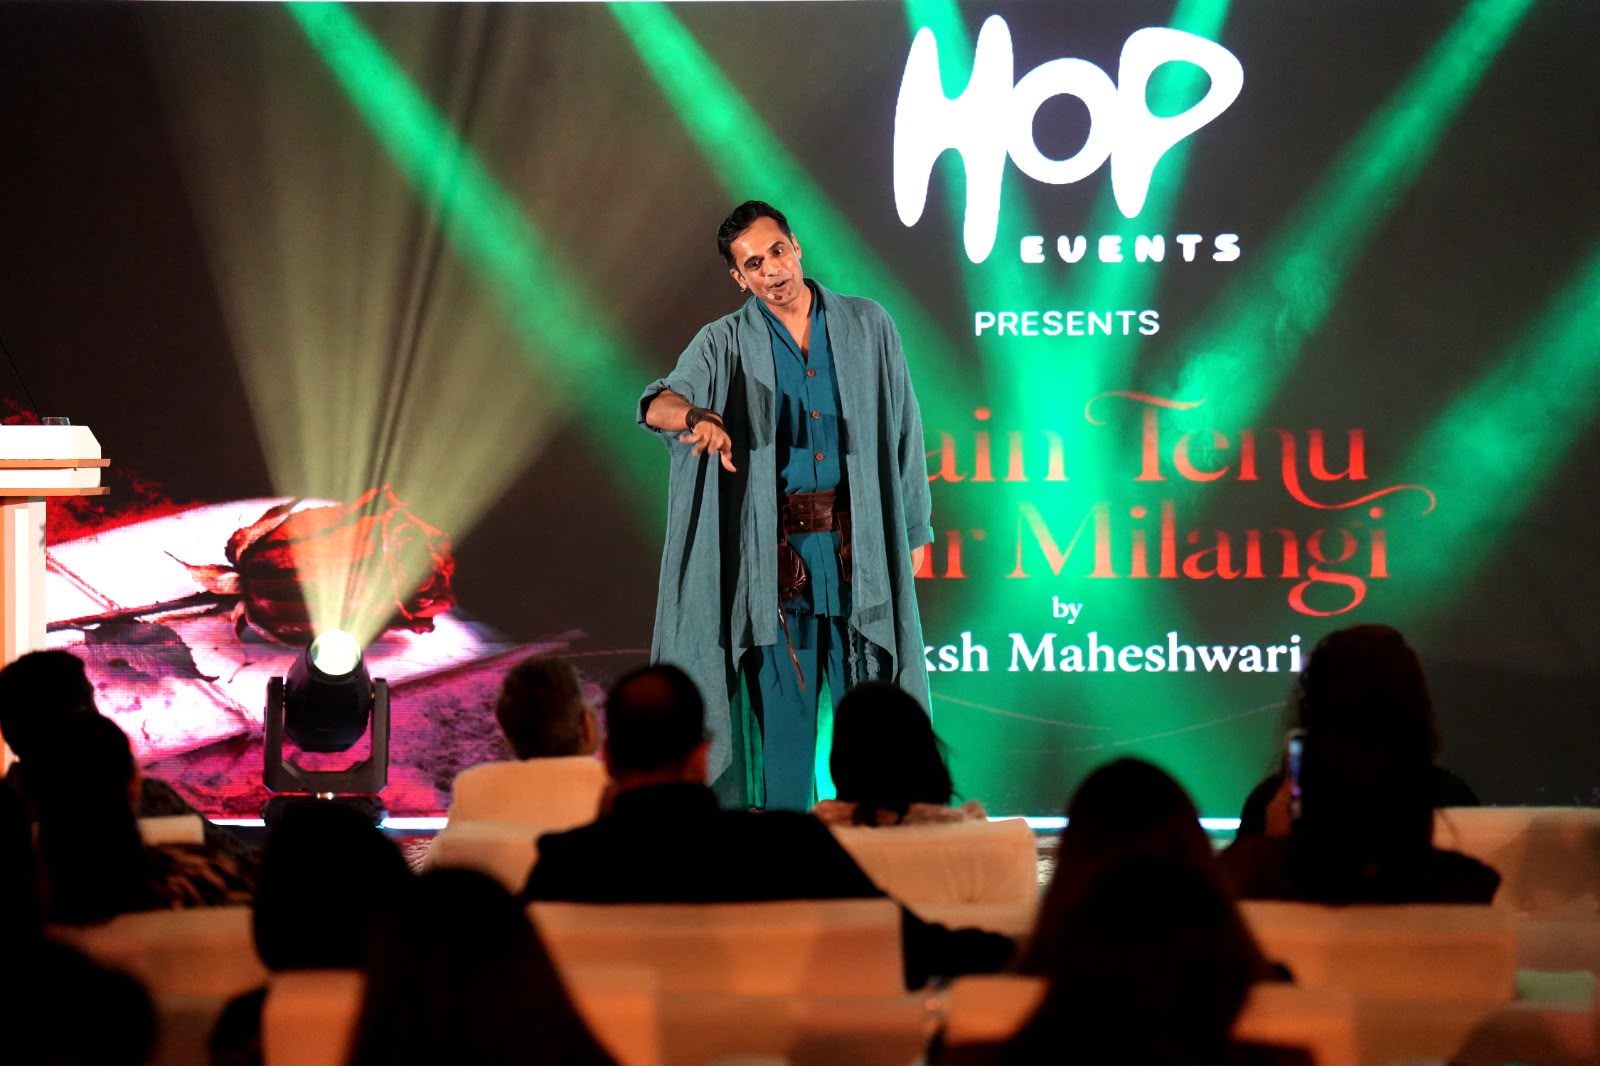
The plans were outlined after a recent Dubai event featuring storyteller Laksh Maheshwari.
HOP is the cultural arm of PANTHEON ACR, a Dubai-based venture founded by Kinariwala with interests spanning art, culture and real estate.
Kinariwala said Dubai’s position as a city with a large international population provided the starting point for HOP’s expansion.
The company said its programme over the next 24 months would feature both established international performers and emerging creative talent, alongside storytelling and other cultural experiences.
“The moments people carry with them for years are rarely the biggest,” Kinariwala said. “They are the moments that make us feel connected, inspired, understood or part of something larger than ourselves.”
Announcements
New-look Abu Dhabi T10 raises the stakes with star-studded 2026 draft; Naseem, Hales, Amir and Shanaka among top picks
Published
1 day agoon
October 2, 2026
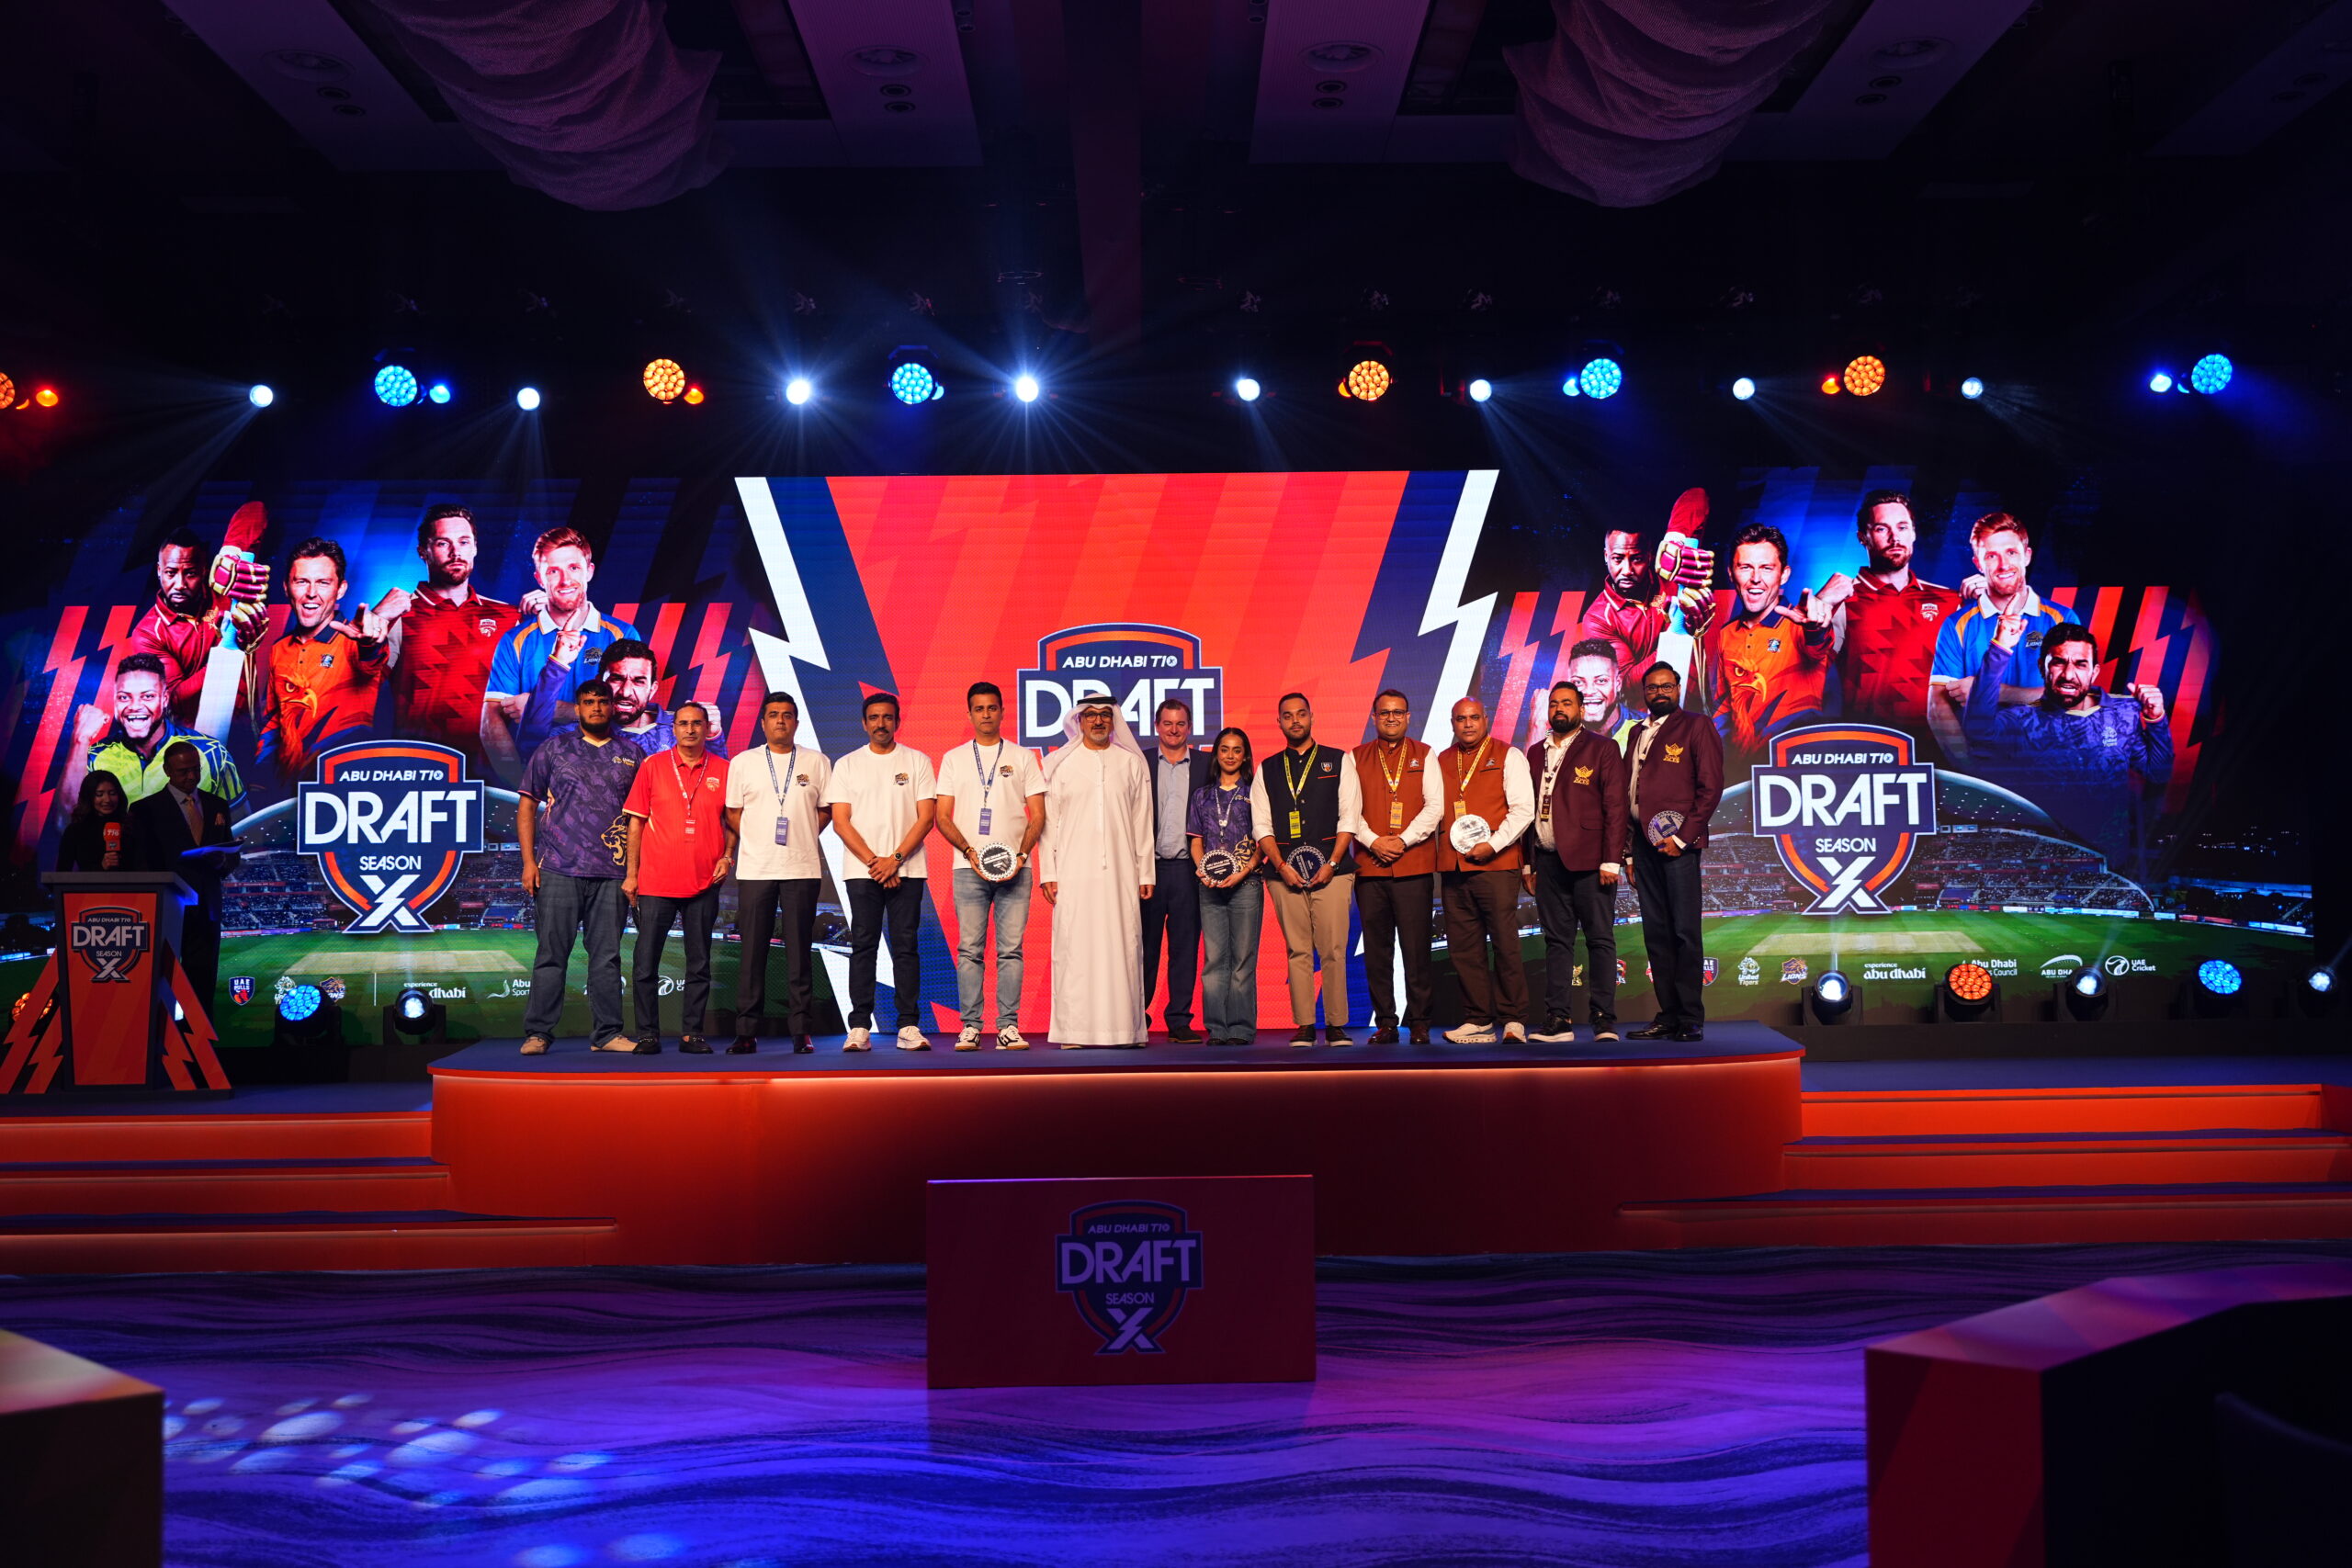
The 2026 Abu Dhabi T10 Player Draft saw a host of international stars find new homes ahead of the upcoming season, with Naseem Shah (Royal Desert Champions), Noor Ahmad (Emirates Eagles), Muhammad Amir (UAE Bulls), Alzarri Joseph (Arabian Aces), Dasun Shanaka (Yas Lions), Shadab Khan (UAE Bulls), Kusal Perera (Emirates Eagles) and Chris Jordan (Royal Desert Champions) among the headline names selected.
The Draft also saw several of the UAE’s leading players join the six franchises, underlining the growing depth of local talent in the reimagined Abu Dhabi T10. Alishan Sharafu (Arabian Aces), Aayan Afzal Khan (Royal Desert Champions), Muhammad Waseem (Royal Desert Champions), Haider Razzaq (Emirates Eagles), Muhammad Rohid (UAE Bulls), Ansh Tandon (Yas Lions) and Luqman Faisal (Emirates Eagles) were among the prominent UAE selections.
Awais Ali Shah (United Tigers), Dhruv Parashar (Royal Desert Champions), Harshit Kaushik (Emirates Eagles), Wali Muhammad (UAE Bulls), Adithya Shetty (United Tigers), Haider Ali (Yas Lions) and Vriitya Arvind (Arabian Aces) were also among those selected, further strengthening the UAE presence across the six squads.
The Arabian Aces will have plenty of experience and firepower in their ranks, with Tom Kohler-Cadmore, Sam Billings and Imran Tahir among their notable draft selections. Alzarri Joseph, Richard Gleeson, Dwayne Pretorius and Dunith Wellalage add further bowling and all-round options to a squad that already featured Moeen Ali, Andre Russell and Liam Livingstone as pre-draft signings. The Aces also secured further local and emerging talent to complement their international core.
The Emirates Eagles’ batting stocks feature Alex Hales, KS Bharat, Hassan Nawaz and Kusal Perera, while David Wiese and Chris Green offer valuable all-round options. Noor Ahmad, Rehan Ahmed and Ali Raza further strengthen the bowling department, complementing pre-draft signings Rovman Powell, Shimron Hetmyer and Trent Boult.
The Royal Desert Champions assembled a formidable side led by the likes of Naseem Shah, Maheesh Theekshana, Dushmantha Chameera and Chris Jordan. Muhammad Waseem, Brandon King and Jayanth Liyanage add batting depth, while Gulbadin Naib and Keemo Paul provide all-round ability. The side already had Nicholas Pooran, Phil Salt and Sherfane Rutherford on board as pre-draft signings.
The UAE Bulls have an abundance of power-hitting options through Andre Fletcher, Aneurin Donald, Khwaja Nafay, Max Bryan and Azam Khan, with Shadab Khan and Khushdil Shah offering all-round depth. Muhammad Amir and Nuwan Thushara add to the bowling attack, while the franchise had already secured Kieron Pollard, Sunil Narine and Romario Shepherd before the Draft. Scotland’s Bradley Currie also joins the squad.
The United Tigers have established international experience with Azmatullah Omarzai, Odean Smith and Mahedi Hasan offering all-round options, while Abbas Afridi and Sufyan Moqim strengthen the bowling resources. The Tigers’ pre-draft haul comprised the Pakistani trio of Fakhar Zaman, Iftikhar Ahmed and Faheem Ashraf.
The Yas Lions have plenty of experience with James Vince, Dasun Shanaka, Tom Moores and Akeal Hosein among their notable selections. Eshan Malinga and Obed McCoy build their bowling strength, while the Lions had already secured Jason Holder, David Willey and Andries Gous before the Draft. Netherlands’ Aryan Dutt also joins the squad as their Associate Member selection.
Arabian Aces: Moeen Ali, Andre Russell, Liam Livingstone, Alishan Sharafu, Muhammad Arfan, Tom Kohler-Cadmore, Richard Gleeson, Sam Billings, Paul Walter, Alzarri Joseph, Imran Tahir, Salman Irshad, Quentin Sampson, Dwaine Pretorius, Vriitya Arvind, Ibrahim Masood, Amshi De Silva, Dunith Wellalage
Emirates Eagles: Rovman Powell, Shimron Hetmyer, Trent Boult, Haider Razzaq, Luqman Faisal, David Wiese, Noor Ahmad, Alex Hales, KS Bharat, Akif Javed, Hassan Nawaz, Rehan Ahmed, Ali Raza, Chris Green, Harshit Kaushik, Hilal Afghan, Toby Albert, Kusal Perera
Royal Desert Champions: Nicholas Pooran, Phil Salt, Sherfane Rutherford, Ali Naseer, Aayan Afzal Khan, Muhammad Waseem, Naseem Shah, Maheesh Theekshana, Dushmantha Chameera, Luke Wood, Gulbadin Naib, Brandon King, Janith Liyanage, Keemo Paul, Dhruv Parashar, Raizal Nadir, Tajinder Singh Dhillon, Chris Jordan
UAE Bulls: Kieron Pollard, Sunil Narine, Romario Shepherd, Muhammad Rohid, Tahir Zaman, Aneurin Donald, Muhammad Amir, Andre Fletcher, Khwaja Nafay, Nuwan Thushara, Khushdil Shah, Mohammad Wasim Jr, Max Bryant, Azam Khan, Wali Muhammad, Uddish Suri, Bradley Currie, Shadab Khan
United Tigers: Fakhar Zaman, Iftikhar Ahmed, Faheem Ashraf, Zeeshan Naseer, Awais Ali Shah, Azmatullah Omarzai, Sufyan Moqim, Abbas Afridi, Odean Smith, Nurul Hasan Sohan, Shak Mahedi Hasan, Habibur Rahman Sohan, Noor ul Rahman, Shamim Hossain, Adithya Shetty, Noor Ullah Ayubi, Paul van Meekeren, Yasin Patel
Yas Lions: Jason Holder, David Willey, Andries Gous, Ajay Kumar, Ansh Tandon, James Vince, Dasun Shanaka, Eshan Malinga, Karim Janat, Sanjay Krishnamurthi, Tom Moores, Khuzaima Bin Tanveer, Obed McCoy, Kamil Pooran, Haider Ali, Masood Gurbaz, Aryan Dutt, Akeal Hosein
Announcements
UAE petrol prices rise again: New fuel rates for October revealed
Published
3 days agoon
September 30, 2026
Filling up in the UAE is about to get more expensive, with petrol and diesel prices rising across all categories from October 1.
UAE motorists are set to feel another pinch at the pump this month after the UAE Fuel Price Committee announced higher petrol and diesel rates for October 2026.
The increase means drivers will pay more per litre across every petrol category, while diesel prices have also moved higher.
Fuel prices for October
The new rates will take effect from Thursday, October 1. Here’s what motorists will pay:
Super 98: Dh4.40 per litre
Special 95: Dh4.28 per litre
E-Plus 91: Dh4.21 per litre
Diesel: Dh4.80 per litre
That means Super 98 rises by 60 fils per litre, while Special 95 and E-Plus 91 increase by 59 and 60 fils respectively. Diesel is up by 50 fils per litre.
How much more will a full tank cost?
For motorists, the increase could quickly add up over the course of a month.
For example, filling a 50-litre tank with Super 98 will cost Dh220 in October, compared with Dh190 in September, a difference of Dh30 per fill-up.
A 50-litre tank of Special 95 will cost Dh214, compared with Dh184.50 previously.
For E-Plus 91, the same tank will cost Dh210.50, up from Dh180.50.
Diesel drivers filling 50 litres will pay Dh240, compared with Dh215 in September.
Why are fuel prices changing?
The UAE Fuel Price Committee reviews retail fuel rates at the end of each month, with prices linked to movements in global energy markets.
UAE fuel prices have experienced notable fluctuations this year. Rates fell in July after several consecutive monthly increases, before moving higher again in August and September.
The latest increase comes amid continued volatility in global and regional energy markets.
What does this increase mean for household budgets?
For people who drive every day, higher fuel prices can have an effect beyond the cost of a single trip to the petrol station.
Commuters, families and businesses that rely heavily on road travel may see their monthly transport expenses rise, particularly if they fill up frequently.
Even a relatively small increase per litre can become more noticeable when multiplied across several refuelling trips over the month.
Dubai-born HOP Events targets 25 cities in global expansion
New-look Abu Dhabi T10 raises the stakes with star-studded 2026 draft; Naseem, Hales, Amir and Shanaka among top picks